Where the service is supplied
The Revenue Department's English VAT page sets the starting point: a service is deemed to be provided in Thailand if it is performed in Thailand, regardless of where it is used, or if it is performed elsewhere and used in Thailand. On that wording the test is where the service is performed, not where the client is. The same page says a person who regularly supplies services in Thailand with annual turnover exceeding ฿1.8 million is subject to VAT; section 81/1 of the Revenue Code exempts a small business below the value set by Royal Decree.
The 0% rate in the Code
Section 80/1 of the Revenue Code lists the businesses taxed at a zero rate. Item (2) is the "provision of services performed in Thailand and used in a foreign country in accordance with the type, rule, procedure and condition prescribed by the Director-General." The Code treats the two separately: section 80/1 sets the zero rate, section 81/1 the exemption; Notice No. 105 applies the 0% rate to a registered business (ผู้ประกอบการจดทะเบียน).
What Director-General Notice No. 105 adds
The Director-General's VAT Notice No. 105 sets those conditions. Clause 2(1) covers a service performed in Thailand for a recipient abroad and used abroad. Where part of such a service is used in Thailand, the 0% rate applies only to the part used abroad. The notice defines the service broadly — any act that can yield a benefit of value, other than the sale of goods — and excludes outbound tour services. Clause 3 then requires evidence of payment of the service fee under the invoice, in the name of the registered business: the notice gives examples such as a letter of credit, a telegraphic transfer (T/T) or T/P, a receipt, a bank statement, a record of a transfer into a bank account, a credit-card payment, or e-money or e-cash.
Currency and language on the tax invoice
Section 86/4 of the Revenue Code lists what a tax invoice must carry and adds that its particulars are made in the Thai language, in Thai currency, with Thai or Arabic numerals — except for certain businesses that need a foreign language or currency, which may do so with the Director-General's approval. Only a VAT registrant may issue a tax invoice at all (section 86/13). A quotation and a plain invoice have no prescribed format on the pages read, so an invoice to a client abroad in English and in the client's currency is not addressed by these sections — the Thai-and-baht rule is written for the tax invoice.
Withholding tax
Withholding is the payer's duty: the Revenue Department's personal-income-tax page describes the payer withholding tax at source and remitting it. The 3% that a Thai company deducts is covered in the withholding-tax guide. The Thai pages read here do not cover whether a client abroad deducts anything.
Worked example
A VAT-registered design studio in Chiang Mai invoices a company in Singapore ฿80,000 for a logo used only in Singapore. Under clause 2(1) of Notice No. 105 the service is taxed at 0%: VAT ฿0, total ฿80,000, reported on the monthly Form VAT 30. The studio keeps the bank record of the transfer, because clause 3 asks for it. If ฿20,000 of the ฿80,000 were for work used in Thailand — say, signage for the client's Bangkok branch — the notice applies 0% only to the part used abroad, and the ฿20,000 part is outside the zero rate.
What GlideQuote does
GlideQuote makes the quotation, invoice and receipt on your phone, with your tax ID and company name printed exactly as you set them once in Business details. Mark the business VAT-registered and the invoice heading becomes a tax invoice; switch withholding tax on for a document and the PDF shows the amount withheld and the net amount due. Each quotation and invoice can carry its own currency, picked from the full currency list, and its own language — English or Thai. Deposits and stage payments are tracked on the invoice, with a receipt for each part payment. The free plan has no card and no time limit; Pro is free for the first month.
This page is general information read from official Thai government pages on 10 November 2026. It is not legal, immigration or tax advice, and it does not tell you what you may or may not do. Confirm your own position with a licensed Thai lawyer or accountant.
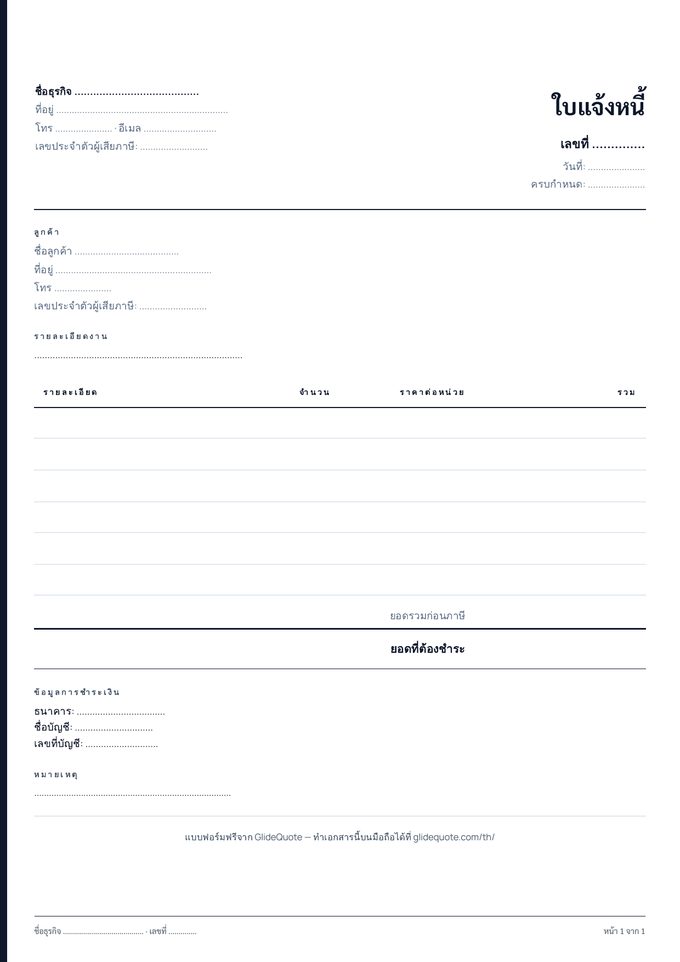 Invoice form (free PDF)A4, Thai, same design as the appAbout the invoice in Thailand →Example, what it must contain, how the app makes it
Do I charge VAT to a client abroad?
What if part of the work is used in Thailand?
What proof do I need for the 0% rate?
Can a tax invoice be in English and in US dollars?
Does a client abroad withhold Thai tax?
Ready to try it?Free plan, no card · Pro is free for the first month